For businesses involved in the purchase, production, or sale of goods, inventory is more than an operational resource. It is an important financial asset whose accurate recording and valuation have a direct bearing on the reliability of financial statements. Whether an organization operates in manufacturing, wholesale, retail, or distribution, effective inventory management is essential not only for ensuring the availability of goods but also for maintaining accurate financial records.
However, inventory accounting is an area where errors can easily occur. Inadequate stock records, inaccurate physical counts, incorrect cost allocation, and failure to recognize inventory losses can result in material misstatements in financial statements. Understanding these errors and their implications is therefore important for business owners, finance professionals, and management.
Understanding Inventory and Its Accounting Treatment
Under International Accounting Standard (IAS) 2, Inventories, inventory generally includes assets held for sale in the ordinary course of business, assets in the process of production for such sale, and materials or supplies to be consumed in the production process or rendering of services. Inventories are generally measured at the lower of cost and net realizable value.
The cost of inventory includes costs of purchase, costs of conversion, and other costs incurred in bringing the inventories to their present location and condition. This means that inventory accounting involves more than recording the amount paid to suppliers. It also requires appropriate consideration of other costs, inventory movements, and potential losses in value.
Common Inventory Errors and Their Effects on Financial Statements
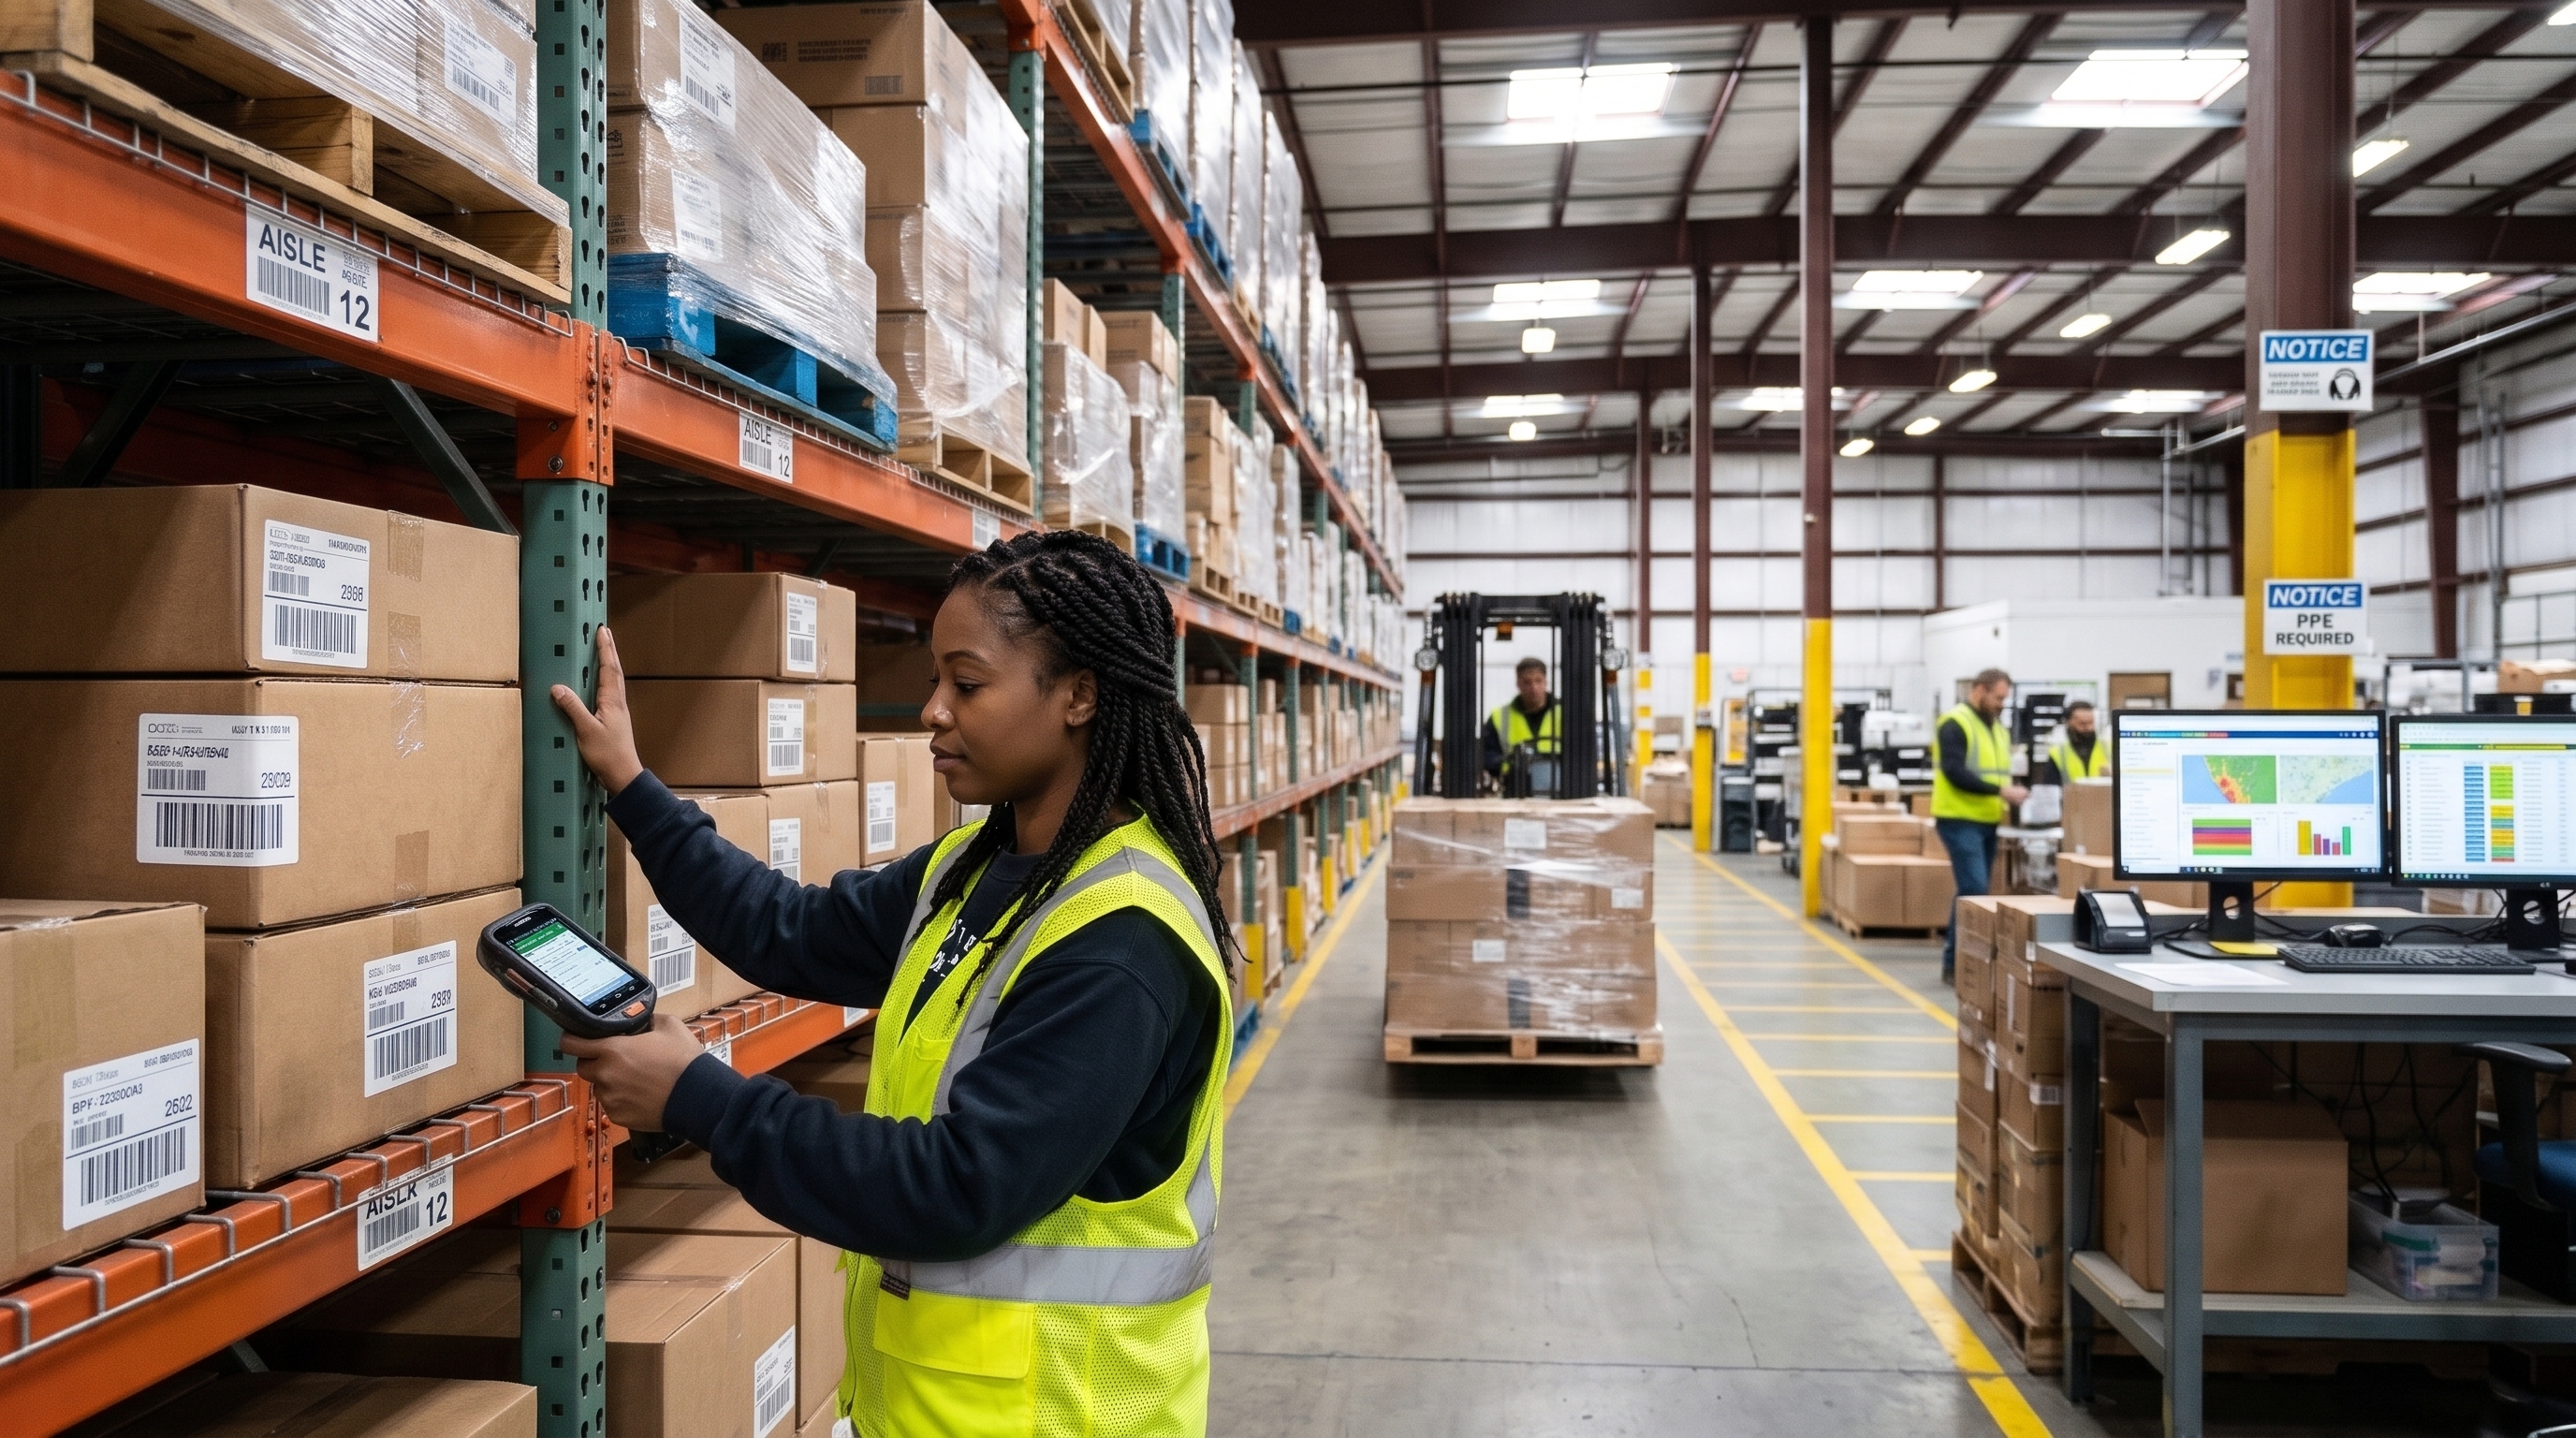
1. Inaccurate Physical Stock Counts: one of the common challenges in inventory management is the failure to maintain accurate physical stock records. Businesses may rely heavily on inventory balances generated by their accounting or inventory management systems without periodically verifying whether those balances agree with the actual quantities held. Differences may arise from theft, damage, breakages, unrecorded issues, errors in receiving goods, or incorrect transaction entries. Where physical inventory is lower than the quantity recorded in the accounting system, failure to investigate and account for the difference may result in an overstatement of inventory and an understatement of cost of sales.
2. Incorrect Inventory Valuation: Another common error is valuing inventory at an amount that does not comply with the applicable financial reporting requirements. IAS 2 requires inventory to be measured at the lower of cost and net realizable value.
3. Incorrect Recognition of Purchases and Sales Around Year-End: The timing of inventory transactions is particularly important when preparing financial statements. Goods purchased or sold close to the end of a financial year may be incorrectly recognized in the wrong accounting period, especially where businesses do not properly review delivery terms and supporting documentation. Businesses should pay attention to year-end cut-off procedures and the contractual terms governing the transfer of control of goods.
4. Failure to Account for Damaged, Obsolete, or Slow-Moving Inventory: Not all inventory held by a business will necessarily be sold at its original cost. Some goods may become damaged, expire, deteriorate, become technologically outdated, or experience reduced market demand. Where the net realisable value of such inventory falls below its cost, an appropriate write-down is required under IAS 2. A business that continues to carry obsolete or damaged inventory at its original cost may present an overstated asset balance and an overstated financial performance. Regular inventory reviews can help management identify these issues early and ensure that appropriate adjustments are made.
5. Incorrect Allocation of Inventory Cost: Inventory costing is not limited to the purchase price of goods. Under IAS 2, the cost of inventory includes costs of purchase, costs of conversion, and other costs incurred in bringing inventory to its present location and condition. For manufacturing businesses, this may include direct labor and an appropriate allocation of production overheads. However, errors may arise when costs that should be included in inventory are excluded or when costs that should be expensed are incorrectly capitalized. Incorrect cost allocation may result in inventory and profit being either overstated or understated.
6. Failure to Maintain Proper Inventory Records: Inventory records should provide sufficient information to establish the quantities received, issued, sold, transferred, and remaining in stock. Where businesses fail to maintain proper inventory records, they may find it difficult to reconcile accounting balances with physical quantities or identify the source of discrepancies. This can also lead to the risk of unauthorized withdrawals, misappropriation, and manipulation of inventory records. An effective inventory management system should incorporate appropriate documentation, authorisation procedures, periodic reconciliations, and independent stock verification.
Inventory management is not just an operational responsibility concerned with ensuring that goods are available when needed. It is also an important aspect of financial management and reporting. Errors in inventory recognition, costing, valuation, and record-keeping can distort a company's financial statements and affect decisions made by investors, creditors, and other stakeholders.
It is paramount, therefore, for businesses to prioritize an effective inventory management control system.