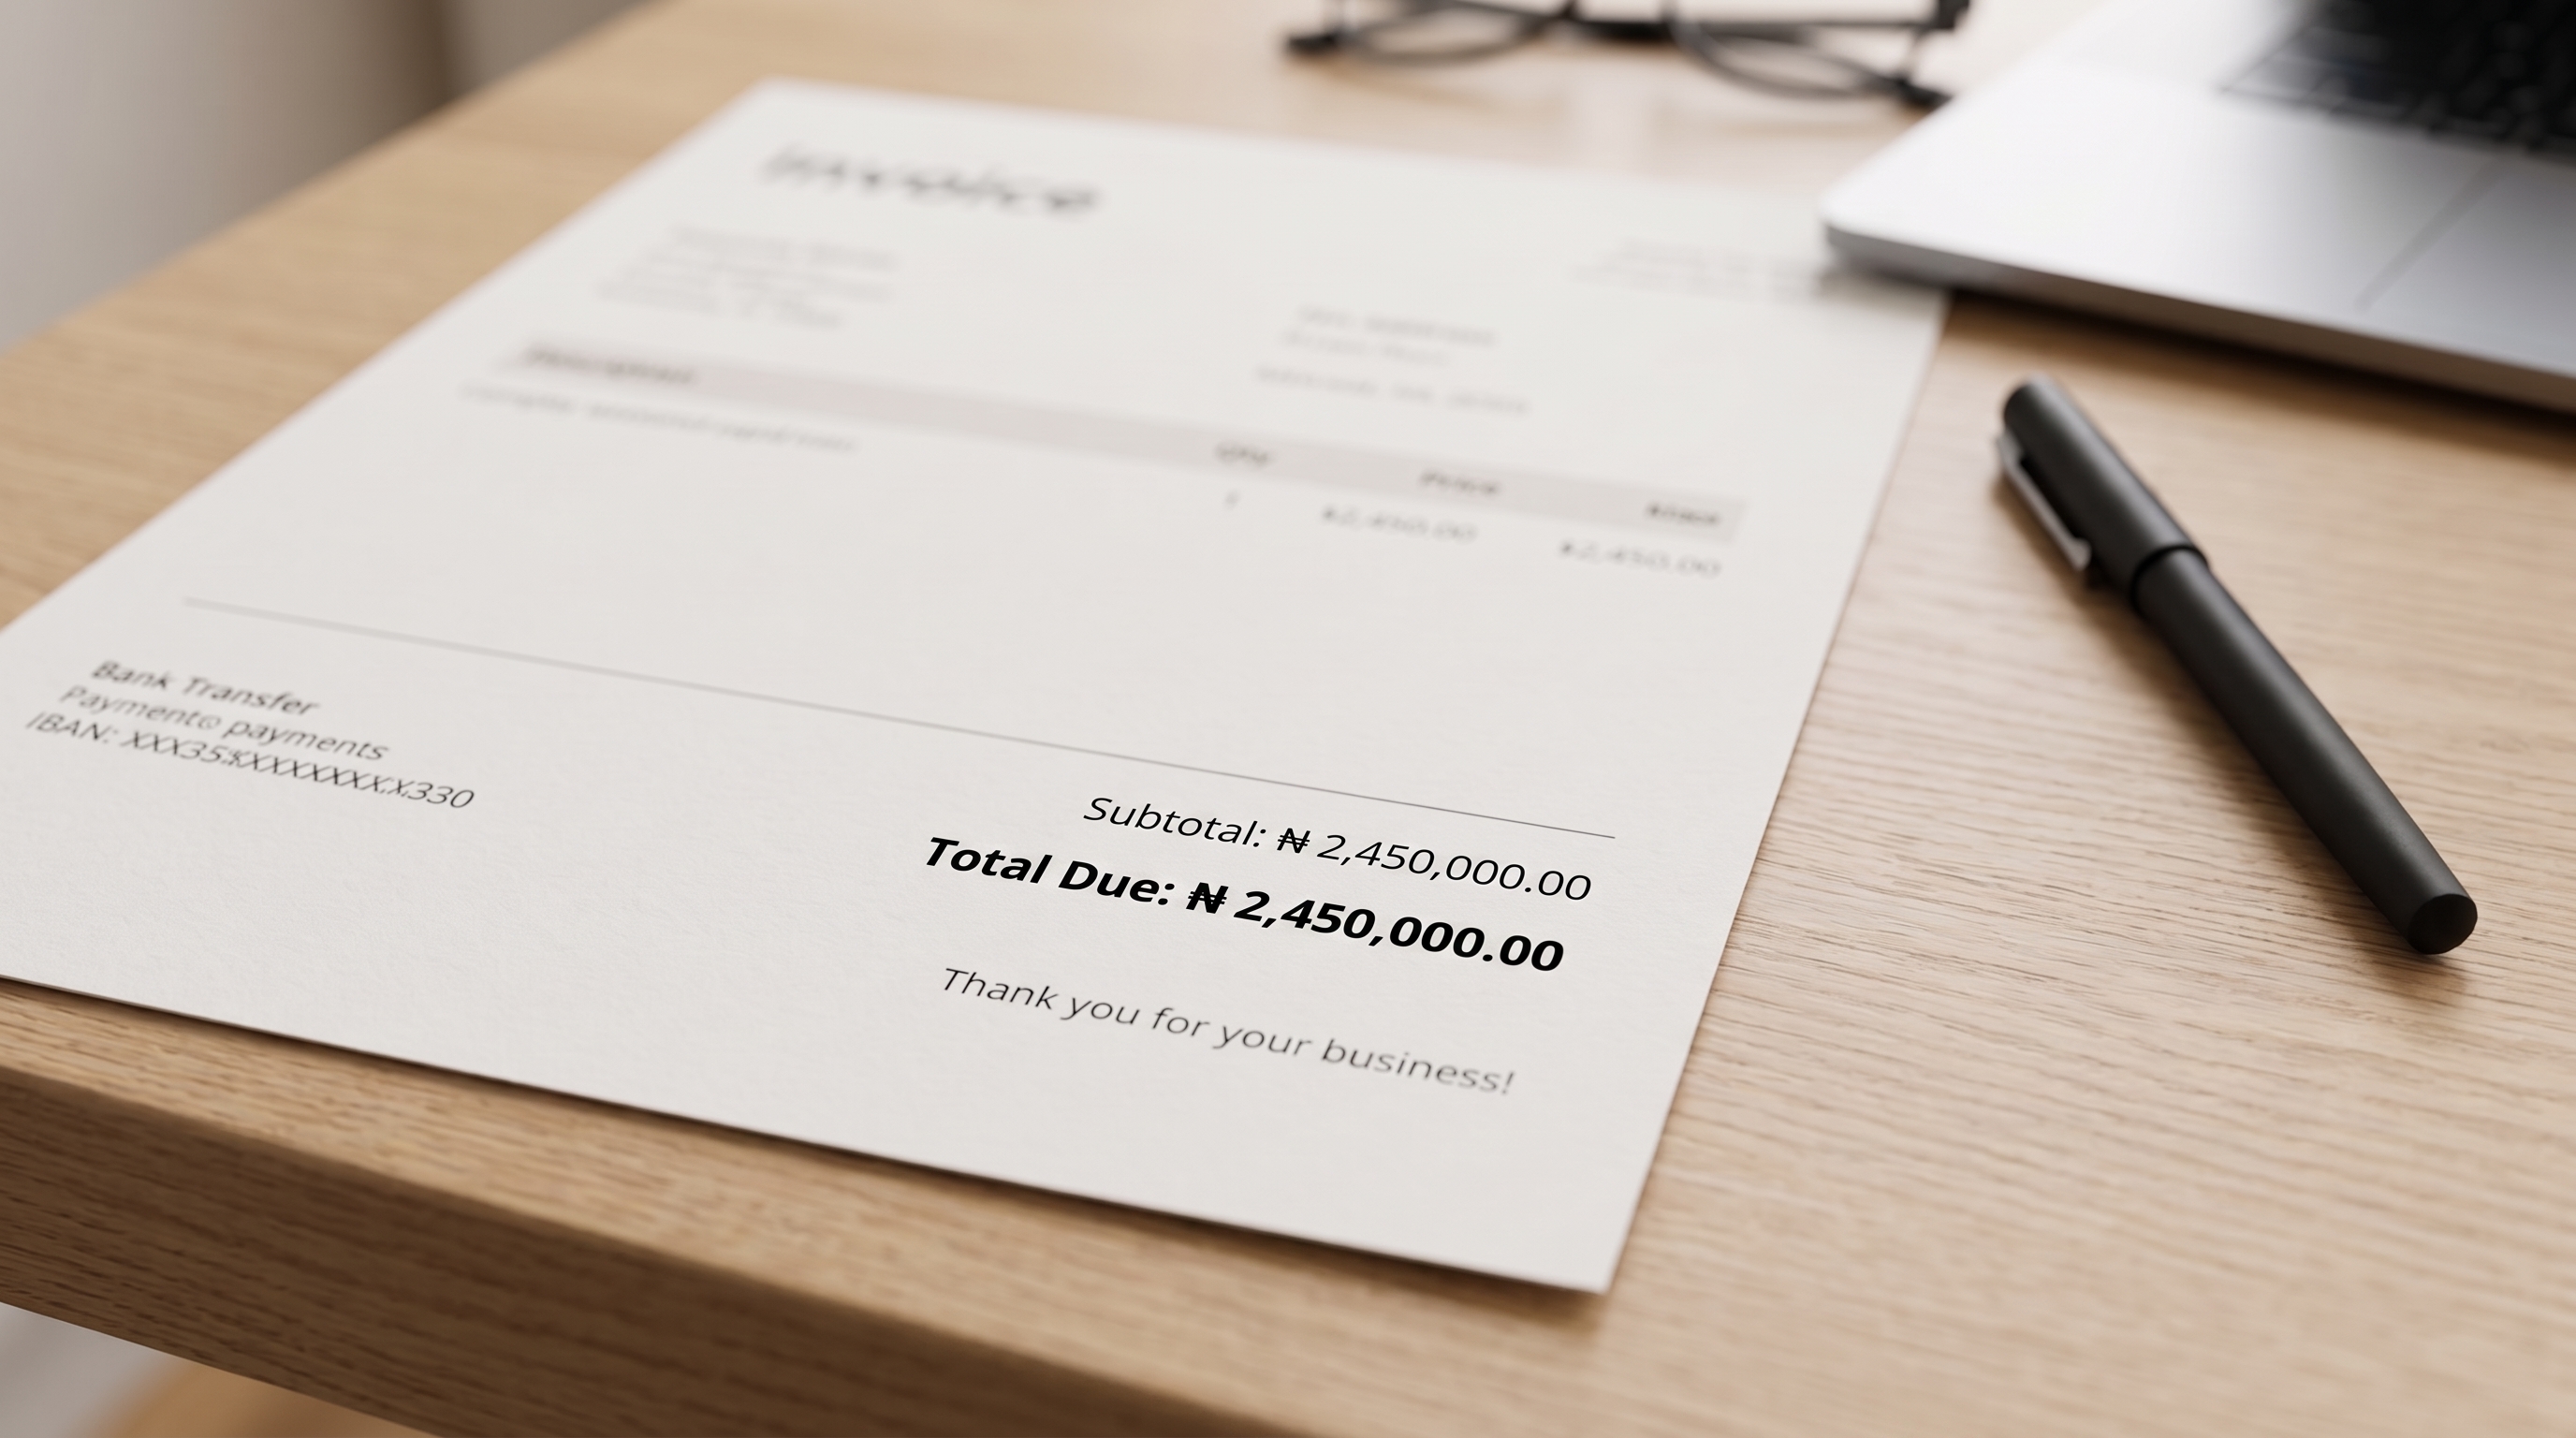
A foreign vendor issues an invoice without a VAT line, and the junior accountant concludes that no VAT is payable. Why is this conclusion risky, and what should be checked before deciding whether to self-account for VAT?
An invoice without a VAT line does not necessarily mean that the transaction falls outside the scope of VAT. It may simply mean that the foreign vendor has not charged VAT. The tax treatment depends on the nature of the supply, the applicable legislation, and the circumstances of the transaction—not just in how the invoice is presented.
A Nigerian recipient may be required to withhold and remit VAT on qualifying taxable supplies made by a non-resident supplier, subject to the applicable statutory provisions. Consequently, an invoice that contains no VAT charge may still give rise to a VAT obligation for the Nigerian recipient. Therefore, the junior accountant's conclusion is risky: the absence of VAT on an invoice is not, by itself, evidence that no VAT is due.
What should you check before self-accounting for VAT?
1. Is the supply taxable in Nigeria?
First, establish the nature of the transaction and whether it constitutes a taxable supply under Nigerian law. Consider the applicable place of supply rules, the nature of the goods or services, and any relevant exemptions or zero-rating provisions.
For services, determine the relevant facts concerning where the services are supplied, the recipient, and where they are used or consumed, as applicable under the legislation.
2. Has the supplier already accounted for VAT?
Determine whether the non-resident supplier is registered or otherwise required to collect VAT, and whether VAT has already been charged or accounted for under an applicable arrangement.
This is particularly relevant to non-resident suppliers of digital services. However, the absence of a VAT line or registration number should prompt further investigation rather than an automatic conclusion that the recipient must self account.
Where VAT has already been properly accounted for, the recipient should establish the correct treatment before making an additional entry to avoid duplicate accounting.
Why this matters to auditors
The financial impact of an error is not always limited to the VAT amount initially overlooked. For businesses that cannot fully recover input VAT, an incorrect assessment may also affect expenses, profitability, and tax reporting. For this reason, the control should not depend solely on the individual accountant remembering to review foreign invoices. A robust process should identify payments to non-resident suppliers, classify the underlying supplies, determine the applicable VAT treatment, and document the basis for the conclusion.
A foreign vendor's invoice may be perfectly valid without a VAT line and still give rise to a Nigerian VAT obligation. Before concluding that nothing is due, establish whether the supply is taxable, who is responsible for accounting for the VAT.